
Our warranty at a glance
Warranty call goes to Michael Bass personally. (385) 247-9359.
2020
Storm Damage Restoration in South Jordan, UT
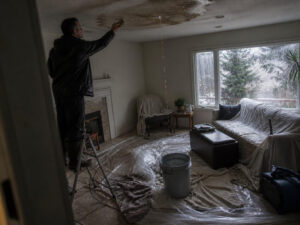
South Jordan’s position at the foot of the Oquirrh Mountains, at the southern end of the Salt Lake Valley on the Wasatch Front, creates a specific storm exposure profile that generates predictable categories of weather damage — on a seasonal calendar that most South Jordan homeowners can recognize but whose consequences they do not always anticipate.
True Day Water Damage Restoration is a licensed Utah Contractor (#960332-3505) and IICRC-Certified Firm (ID #927354-5258), based at 11268 S 2865 W in South Jordan. We provide complete storm damage restoration throughout Salt Lake County. Call us at (385) 247-9359.
South Jordan’s Storm Damage Calendar
January and February — Ice Dam Season
The Wasatch Front’s freeze-thaw cycling — overnight lows well below 0°C (32°F), daytime temperatures recovering above freezing — creates ice dam conditions on the low-slope and flat residential rooflines common in South Jordan’s contemporary craftsman and modern farmhouse construction. The buildup of ice dams allows meltwater to seep beneath roofing membranes and into attic spaces, leading to saturated insulation and oriented strand board used for roof sheathing. The water appears inside the home as ceiling stains, wet drywall, or drips — often days after the ice dam formed, making the source non-obvious to visual inspection. FLIR thermal imaging cameras are used to trace the moisture migration pathway from the ice dam entry point through the attic assembly to the affected interior ceiling surfaces.
March Through May — Snowmelt Flooding
Snowmelt runoff from the Oquirrh Mountains saturates South Jordan’s expansive clay soils — the montmorillonite-rich smectite lacustrine deposits left by ancient Lake Bonneville — raising the groundwater table and increasing hydrostatic pressure against basement foundations. Properties in lower-elevation corridors near the Jordan River floodplain experience basement seepage and sump pump overload during high-snowpack spring melt seasons. Storm restoration in this period involves water extraction, structural drying, and foundation assessment.
July Through September — North American Monsoon Season
The North American Monsoon pattern — the seasonal moisture flow from the Gulf of California that generates intense convective precipitation events across the Intermountain West from early July through mid-September — produces South Jordan’s most acute storm events. Rainfall rates of one inch per hour or more are recorded during significant monsoon cells. The resulting flash flooding overwhelms residential drainage systems, saturates window wells, and enters basements through below-grade windows and foundation penetrations. Monsoon events also produce the hail damage and wind damage to roofing and siding that generates significant storm restoration demand in the south Salt Lake Valley each summer.
October and November — Late Season Wind Events
Autumn windstorms — driven by pressure gradient between the high desert and the valley floor — can produce localized wind damage to roofing, siding, fencing, and trees that impact structures. Wind-driven rain through compromised roofing or siding creates water intrusion into wall and ceiling assemblies that may not be immediately apparent.
- Does insurance cover ice dam damage?
- Most HO-3 and HO-5 policies cover ice dam meltwater intrusion as weather-related water damage. Documentation of the ice dam entry pathway and resulting mold conditions supports the claim. The insulation deficiency is not covered — the resulting water damage is.
- Does insurance cover monsoon flooding?
- Outdoor flooding through window wells or exterior foundation is excluded under the flood exclusion. Municipal sewer surcharge backflowing through internal drain fixtures may be covered under a sewer backup endorsement. Wind-driven rain through a storm-damaged roof or flashing is typically covered as windstorm damage.
- Should I use tarps after storm roof damage?
- Yes. Tarping prevents continued water intrusion until repairs proceed. Broken windows and compromised wall sections require board-up. Both are covered as mitigation expenses under the Duty to Mitigate provision of the storm damage claim.
Our Storm Damage Restoration Services
Storm damage restoration covers the full sequence from emergency response through complete reconstruction:
- Emergency tarping and board-up of storm-compromised roof and wall openings
- Water extraction from storm flooding and ice dam intrusion
- FLIR thermal imaging to map moisture migration from storm entry points
- ANSI/IICRC S500-compliant structural drying with daily moisture monitoring
- Mold prevention antimicrobial treatment of affected structural assemblies
- Licensed general contractor reconstruction — roofing, siding, drywall, insulation, flooring, painting
- Complete insurance claim documentation and adjuster communication
Learn more about our water damage restoration, basement flooding cleanup, mold remediation, reconstruction services, and insurance claims assistance.
True Day Water Damage Restoration | 11268 S 2865 W, South Jordan, UT 84095 | (385) 247-9359 | License: #960332-3505 | IICRC: #927354-5258
Certified
Firm
Pay Over Time Through Wisetack — No Hit to Your Credit to Check
Insurance covers most restoration jobs. For the deductible, non-covered scope, or jobs filed out-of-pocket, True Day offers financing through Wisetack — a homeowner-friendly lender with soft-credit prequalification (checking your rate does not affect your credit score).
Your True Day project manager can prequalify you in a few minutes during the written-scope visit. Nothing to sign on the spot.
About Wisetack: loans are issued through independent lending partners. Rates and approval depend on your credit profile. Prequalification is a soft inquiry; final approval may involve a hard inquiry. True Day does not profit from or receive referral fees for financing.
What True Day guarantees on every job
Utah’s two biggest water-damage seasons
Most of the water losses we see in South Jordan cluster into two windows a year. Here is what to inspect before each one.
Snowmelt Mar–Apr
The Wasatch snowpack hits our valley all at once. Combined with Bonneville clay soil (slow infiltration) and old perimeter grading, that water finds basement windows and foundation cracks.
- Test the sump pump — run water into the pit; it should kick on at the float
- Clear window well drains and gutters above them
- Walk the yard: regrade any dirt that slopes toward the foundation
- Check basement rim-joist and corner cracks for staining from last year
Pre-freeze Oct–Nov
Utah’s first hard freeze catches homeowners who forgot one exposed line. The classic failure is a burst supply line inside an exterior wall or in a crawl space.
- Pull and store garden hoses; cap exterior hose bibs with foam covers
- Insulate any pipe you can touch in your crawl, attic, or garage ceiling
- If leaving the house for winter: set thermostat no lower than 55°F, shut the main water valve, open interior cabinet doors
- Know where your main water shutoff is — before an emergency, not during one
If you discover a problem on inspection, we offer free emergency inspections 24/7 at (385) 247-9359. Prevention tips here are not a sales pitch — the best job is the one you did not need us for.
Storm damage restoration FAQ
What is covered on a standard homeowners policy, what is not, and how to sequence the trades when rain is still coming in.
What’s covered on a storm claim vs. not covered?
What is an ice dam and why does it leak?
Who do I call first — a roofer or restoration?
How much does storm damage cleanup cost?
How fast can you respond during a storm?
What about the exterior damage — siding, roof, gutters?
Winterize before November — 7 steps that prevent a freeze-burst loss
Utah’s first hard freeze catches homeowners who forgot one exposed line. Run through these before Halloween each year.
Disconnect and store garden hoses
A connected hose keeps the exterior bib and the first several inches of pipe below freezing-safe. Even a frost-free sillcock will burst with a hose attached. Pull them all before the first freeze.
Cap exterior hose bibs with foam covers
Styrofoam faucet covers from any hardware store run around $2 each. They keep the bib and the stub of pipe behind it above freezing even when the air drops.
Insulate pipes in unconditioned space
Any pipe you can touch in a crawl space, attic, or garage ceiling. Foam pipe sleeve is cheap and 15-minute install. Priority: supply lines along exterior walls, lines through crawl-space corners, hot-water line in the garage.
Blow out the sprinkler system
Shut the sprinkler supply valve inside the house. Run an air compressor through the backflow preventer to purge water from every zone. Residual water in a buried head or an above-ground backflow is the single most common freeze claim we see.
Open cabinet doors under sinks on exterior walls
On the coldest nights (sub-20°F forecast), open the cabinet doors below kitchen and bathroom sinks that sit against exterior walls. Lets warm house air reach the supply lines. Costs nothing.
Leave a trickle on vulnerable fixtures
When a hard freeze is forecast, let the farthest-from-the-water-heater fixture drip cold water pencil-thin overnight. Flowing water does not freeze as easily as still water. One fixture is usually enough; running them all wastes water.
If you leave the house for the winter: thermostat, shutoff, cabinets
Set thermostat no lower than 55°F. Shut the main water valve to the house. Drain down to the lowest fixture (or hire a plumber to winterize if you’re gone more than two weeks). Open interior cabinet doors on exterior walls. Tell a trusted neighbor to call us if they see water running from a soffit vent.
If something freezes despite the prep, close your main shutoff immediately and call (385) 247-9359. Catching a freeze-burst in the first hour vs. the first day is the difference between a one-day job and a one-week job.
Leaving your Utah home for the winter — 9-item departure checklist
For snowbirders, extended travelers, and anyone leaving the house empty for more than two weeks in cold weather.
Set thermostat no lower than 55°F
Below 55 and interior pipes along exterior walls can start freezing. 55 is the industry baseline for “empty house in winter.” If energy cost matters, 60 is safer; 50 saves nothing worth the risk.
Shut the main water valve
If no one is home to catch a leak, water that never enters the house can’t flood it. This single step prevents more losses than any other item on this list.
Drain or vacation-mode the water heater
Either drain the tank fully, or set it to vacation / pilot-only mode. A full-pressure tank sitting cold for months can develop pinhole leaks that only show when you turn the main back on.
Open interior cabinet doors on exterior-wall sinks
Even with the main off, residual water in the trap and under-sink line can freeze and crack. Open doors let residual heat reach them.
Open bathroom faucets slightly
After shutting the main, open each faucet to the lowest trickle setting to let residual pressure escape and let any slow freezing push out rather than crack the line.
Pour non-toxic antifreeze into traps if going below 20°F
Sink, tub, shower, and floor drain traps hold water that can freeze and crack the P-trap. RV / plumbing antifreeze (propylene glycol, pink) is safe for home traps — 1 cup per trap.
Unplug electronics and non-essential appliances
Surge protection + fire protection + saves standby power. Keep the refrigerator plugged in only if you’re leaving food in it (otherwise clean it out, prop door open, unplug).
Arrange a trusted neighbor for weekly drive-by
Show them where the main water shutoff is, the circuit breaker panel, and give them your contact + an emergency restoration number. A $20 thank-you gift and a photo tour of the key valves can save tens of thousands.
Save our number to the neighbor’s phone
Give them (385) 247-9359 as the emergency restoration number. If they see water pouring from a soffit vent or your mail turning brown, we respond on their call — we don’t need you on the line from Arizona.
Winterization service: If the above list is more than you want to handle yourself, hire a licensed plumber to professionally winterize (full line blowout). On an older or more complex home it’s worth the fee.
Utah storm damage: two seasons, three failure paths
Storm damage in the Salt Lake Valley has distinct seasonal and failure patterns. Monsoon storms (July-September) produce flash wind and intense rain over short periods; winter storms (November-February) produce prolonged ice loading, wind-driven snow, and freeze-thaw cycles. The three failure paths that produce water-damage claims — roof envelope, wall envelope, and surface flooding — each need a different first response.
Monsoon season storms (July-September)
Pattern: short-duration (30-90 minute) rotation events with 1-3 inches of rain in a localized area, often with 40-60 mph wind gusts and sometimes hail. Clear sky before and after. The intense short burst overwhelms drainage designed for steady-rain climates.
Common failures: gutter overflow (water driven under roof edge or against siding), clogged downspouts (water pooling around foundation), window-well drains overwhelmed (basement intrusion), skylight gasket failure, flashing failure around roof penetrations, wind-driven rain through soffits.
Winter storms (November-February)
Pattern: prolonged events — days of accumulation, freeze-thaw cycles, ice-dam formation at eaves. Lower-intensity moisture per hour but much longer dwell time against the structure.
Common failures: ice damming on roof eaves (water backs up under shingles into attic and ceiling), roof-load snow accumulation causing shingle lift, frozen gutter runoff finding paths into fascia and soffit, wind-driven snow infiltrating attic vents, chimney flashing failures from freeze-thaw stress.
What we do on arrival for storm-caused water intrusion
- Secure the envelope first. If the storm is still active or recent and the entry path is still open — roof hole, broken window, failed skylight — emergency tarping or board-up stops additional water before extraction begins. This is non-negotiable sequence: securing comes before drying.
- Trace the actual entry path. The visible interior damage is often not directly below the exterior failure. Water travels along rafters, down wall cavities, and across ceilings before showing. Thermal imaging on the ceiling and walls traces the actual path.
- Document for your carrier. Storm damage claims require both the storm event (date, weather service confirmation) and the specific failure. We photograph the exterior failure point, the interior migration, and the moisture mapping — the carrier needs all three to approve the full scope.
- Begin extraction and drying under normal S500 protocol. Storm-source water is usually Category 1 (clean rain, melted snow) unless it carried organic debris or hit soil before entering — then Category 2. We assess on arrival.
- Coordinate with your roofer or siding contractor. Our scope ends at the envelope repair; a licensed Utah roofer handles the permanent repair. We help sequence the work so interior drying and exterior repair don’t block each other.
Insurance notes specific to storm damage
- Standard Utah homeowners policies cover sudden storm damage. "Act of God" isn’t an exclusion category; the policy treats it as a covered peril.
- Hail damage to the roof is typically covered under a separate wind/hail deductible that is higher than your standard deductible (often 1-2% of dwelling value). Check your dec page.
- Flood damage from rising surface water is NOT covered under standard homeowners — that requires a separate flood policy (NFIP or private flood). The distinction matters: wind-driven rain through a failed roof is covered; the same water rising from below after it reaches the ground is not.
- Documentation of the storm event helps. NWS storm reports, local news coverage, and timestamped photos of the exterior failure are all useful. We help assemble the file for the carrier.
Storm damage — frequently asked questions
What happens when a Utah storm or freeze warning hits the whole valley
Our standard response commitments (45 minutes in South Jordan, 60-90 minutes in adjacent cities) are built around normal operating conditions. During a declared severe weather event — a hard-freeze week in January, a flash-flood monsoon event in July, a major storm with widespread damage — call volume spikes across the whole valley at the same time. Here is honestly what happens, and how we communicate with homeowners during these events.
Pre-event preparation (24-72 hours ahead)
When NWS Salt Lake City issues a watch or warning that is likely to drive loss volume (hard-freeze week with sustained <15°F temperatures, flash flood watch during active monsoon rotation, severe thunderstorm warning with hail), we start pre-event preparation:
- All trucks loaded with full extraction, drying, and demo complement — not partial for the normal daily job pattern.
- Equipment pre-staged at our shop beyond what trucks carry — additional LGR dehumidifiers, air movers, HEPA scrubbers ready to deploy as follow-on.
- On-call crew expanded to maximum coverage.
- Rental agreements with regional restoration equipment vendors confirmed for scale-up capacity.
During the event — what we tell callers honestly
If you call us during an active severe weather event with heavy loss volume across the valley:
- You still reach a live person. The 24/7 live-answer commitment doesn’t suspend during events.
- The dispatcher takes the loss information and gives you a realistic ETA based on where the current crews are deployed. "45 minutes" may become "3 hours" during peak event volume — and the dispatcher will tell you that honestly rather than promising a time we can’t hit.
- If the ETA is longer than you want to wait and the loss is serious, we tell you what to do yourself to limit damage until we arrive, and we can recommend another IICRC Certified Firm who may be closer or less loaded. Honest handoff beats a long wait on a promise.
- If you choose to wait, we honor the realistic ETA we gave you — not the standard 45 minutes.
Weather-event exclusions from the arrival guarantee
The dehumidifier-waiver remedy on our standard response-time guarantee has one explicit exclusion: declared NWS weather events (blizzard, flash flood, red-flag warning, winter storm warning). Those events change the operating conditions enough that the standard commitment can’t be guaranteed. The exclusion is logged and documented on event days — we publish the NWS event summary with the monthly response-time report so the exclusion is auditable, not just a verbal rule.
Why we prefer honest ETA over queue secrecy
The alternative — telling every caller "on the way, 45 minutes" when the real ETA is 4 hours — produces angry 1-star reviews and homeowners who could have made a better decision if they’d known the truth. On event days we triage honestly: shorter ETA for the Daybreak basement that’s actively flooding; longer ETA for the Sandy call where the water is already stopped and the loss is contained. The dispatcher explains the triage logic so the slower-ETA caller understands why.
Four Utah storm patterns that produce water losses in South Jordan
“Storm damage” sounds like one thing. The water your insurance company sees is actually four different events, each with a different intrusion mechanism, a different IICRC water category, and a different coverage path.
Snowmelt ice-damming (Jan–Mar)
Daytime sun melts rooftop snow; refreezes at the colder eave; dammed water backs up under shingles and enters the attic or top-floor ceiling. Common in older SJ builds with under-insulated attics.
July–September monsoon burst
Short, intense thunderstorm cells drop 0.5–1.5 inches of rain in under an hour. Overwhelms gutters and downspouts, saturates landscape beds against foundations, and the water enters through foundation seams or window wells.
Wind-driven rain and sideways-wet walls
Spring and fall frontal systems push rain horizontally against west-facing walls. Water finds the slightest siding or window-flashing gap, enters wall cavities, and emerges a day or two later as interior staining or baseboard warping.
Hail-flashing failure
Hail damages roof flashing around chimneys, vents, and skylights without visibly damaging the shingles. The failure point only reveals itself at the next heavy rain, which can be weeks later. By the time the leak shows, the hail event is harder to tie to the loss.
Utah storm damage — what’s covered vs. the flood exclusion
Utah storms produce specific damage patterns that affect what’s covered by standard homeowner policies. The split between “sudden wind/hail” and “flood water” decides which claims pay.
Utah storm patterns and typical coverage
- Hail — late spring and summer thunderstorms. Roof shingle damage, siding damage, broken windows, car damage. Covered under standard homeowner policies. Separate deductible may apply to wind/hail (often 1-2% of insured value, not flat).
- Straight-line wind + microbursts — also summer thunderstorms. Downed trees, torn-off siding, roof damage. Covered.
- Downed-tree water intrusion — a tree falls on the roof, water enters. Covered as a sudden-and-accidental event, including the water damage after.
- Wind-driven rain through a damaged roof — if the wind damaged the roof first, water that enters after is usually covered. If the roof was already damaged and failed in a normal rain, carriers may push back.
- Snowmelt flooding into basement — typically excluded under the flood exclusion. Requires separate NFIP or private flood policy.
- Ice dam water intrusion — covered as sudden-and-accidental water damage, since the ice dam is a sudden weather event.
- Lightning strikes — covered, including fire damage and electrical surge damage to appliances/electronics.
- Combined-sewer backup after storm — sewer-backup rider required (see our sewage cleanup page).
What our storm response includes
Emergency board-up and tarping (see board-up page), water extraction and dry-out on interior water, structural assessment on wind/tree damage, documentation of weather event + damage for the carrier (NOAA/NWS records matter), reconstruction under our Utah GC license.
Timing matters on storm claims
Mitigation (board-up, tarping, water extraction) must happen fast or carriers can deny for failure-to-mitigate. We dispatch 24/7/365.
What’s covered after a Utah storm — decision tree
Follow this flow to figure out which coverage applies to your specific storm damage.
Step 1: Is damage from the storm event itself (wind, hail, lightning) or from water that entered?
- Direct wind/hail/lightning damage (roof shingles, siding, broken windows, downed trees, electrical surge) → standard homeowner policy, likely covered. Separate wind/hail deductible may apply (1-2% of insured value typical).
- Water that entered after wind damage → also covered, usually under the same claim as sudden-and-accidental water damage secondary to the wind event.
- Water from flooding (exterior ground water) → typically EXCLUDED under flood exclusion. Separate NFIP or private flood policy required.
- Water from sewer backup during storm → requires sewer-backup rider on your policy.
Step 2: If water entered the home, how did it get in?
- Through a wind-damaged roof → covered under the wind damage.
- Through a wind-damaged window → covered under the wind damage.
- Through an ice dam (January-February) → covered as sudden-and-accidental water damage from the ice dam event.
- Through foundation seepage from saturated ground → typically excluded as flood.
- Up through floor drain from combined sewer → sewer-backup rider required.
- Through a window well that overflowed → case-by-case; sometimes paid, sometimes denied as flood.
Step 3: Is there structural damage requiring immediate mitigation?
If yes: emergency board-up / tarping / water extraction must happen FAST, or carrier can deny for failure to mitigate. Call us; we dispatch 24/7/365.
Step 4: Document weather event with NOAA/NWS records
Hail size, wind speed, storm date can be verified against NOAA records. We attach these to our documentation. Weather-event verification is often what moves a borderline claim from denied to paid.
How we figure out whether it was hail, wind, or rain — and why it matters
Insurance policies treat these three differently. A policy may cover hail with a separate higher deductible, cover wind under the standard deductible, and only cover rain damage if it entered through a hail or wind opening. If we misattribute the cause, your claim could be denied or paid incorrectly. Here’s how we read the evidence on arrival.
| Source | Signature on the roof | Signature inside |
|---|---|---|
| Hail | Round impact marks on soft metal (gutters, flashing, vents, A/C fins); granule loss on shingles; dented soft asphalt in random pattern | Water entry concentrated under impact points; often spotty across the ceiling, not a single stream |
| Wind | Lifted or missing shingles; creased shingles that didn’t break but hinge-folded; torn ridge cap; blown-off flashing | Water entry along a wind line (one side of the house); often with debris blown into the attic (leaves, insulation displaced) |
| Rain only | No impact marks, no missing shingles; soffit vents or gaps let water in during horizontal rain; blocked gutters overflow into fascia | Slow drip through soffit/fascia; stain on top plate; often under gutters rather than at ridge |
Why we photograph the exterior first, before any interior work
- Insurance adjusters look at the roof and exterior for cause-of-loss determination — our interior work shouldn’t disturb that evidence
- We take dated photos with wide-shot context (which side of the house, which section of roof) and close-ups of the impact or lift evidence
- If we can’t safely access the roof (steep pitch, icy conditions), we document from the ground and from windows — we don’t guess
If exterior damage looks like it might involve roof replacement scope, we’ll flag that for the adjuster or recommend a roofer — we don’t do roofing ourselves. Our side is the interior water mitigation and the restoration of what the water damaged inside.
What we do when a storm is still happening — temporary mitigation specs
Permanent repair can’t happen until the storm ends. But if your roof has a hole or a window is broken while the storm is still active, waiting makes everything worse. Temporary mitigation closes the opening and buys time — here’s what proper temp mitigation looks like, not just a tarp thrown on a roof:
| Opening | Temporary measure | How long it lasts |
|---|---|---|
| Hole in roof (hail, wind, tree branch) | 6-mil poly or heavy-duty tarp with 2×4 battens, screwed into the deck through the shingle layer (holes seal when permanent repair happens) | Up to 90 days when properly installed; UV degrades thin tarps faster |
| Missing shingles | Peel-and-stick ice-and-water underlayment over the affected area; secured with roofing nails | Up to 6 months; it IS a waterproof barrier, not just a cover |
| Broken window (small) | Clear 6-mil poly on the interior, taped and framed; plywood on the exterior if security is a concern | Lets light in; up to 2-3 weeks before poly starts to tear |
| Broken window (large) or sliding door | 3/4" OSB cut to size, lag-screwed into the frame; weatherstripped at edges | Up to several months; secure against trespass as well as weather |
| Siding ripped off | Heavy-mil poly stapled or tacked over affected area, overlapped and taped at seams; battens if wind is still active | Up to 30 days; longer and the poly loses UV stability |
| Garage door blown in or torn off | OSB panels secured in track openings; studs added if structural movement happened | Short term — schedule garage-door contractor as soon as storm passes |
What temp mitigation protects
- Interior from additional water damage during continued rain
- Property from secondary losses (wind entering through hole, animals getting in, trespass)
- Your insurance coverage — policies require “reasonable steps to prevent further damage,” which temp mitigation satisfies
What temp mitigation doesn’t do
- Isn’t a permanent repair — it buys time; roofing/window/siding contractors still need to come after the storm
- Doesn’t restore cosmetic appearance — it’s functional, not pretty
- Doesn’t address interior water that already got in — that’s a separate mitigation scope that starts the same visit or next
How we schedule during active weather events
- During major storms we triage temp mitigation calls alongside interior-water calls — both are urgent in different ways
- If demand exceeds capacity (significant hail event, for example), we’ll be direct about ETA and may recommend you handle temp measures yourself with our guidance until we can get there
- We don’t climb a roof in active high winds, lightning, or on heavy ice — safety limits dispatch during the worst of the weather
When a tree hits your house: scope + sequence of operations
Tree-impact damage during a storm is one of the most complicated storm scenarios we respond to — because the tree has to come off before any permanent work can happen, but water intrusion starts the moment the roof is compromised. The timing of each party involved matters. Here’s how it typically runs:
- Safety: evacuate affected rooms, confirm no one is injured, call 911 if anyone is
- Power: shut off at breaker to affected area (fallen tree may have taken power lines)
- Rocky Mountain Power called if lines are involved — they handle de-energization before anyone else works
- Call us + a tree service in parallel — both responses need to start as fast as possible
- Tree service begins extraction when safe; we begin temp-tarp and interior containment the moment the tree is clear enough for us to work safely under the roofline
What each party does
- Tree service: removes the tree in sections, protects remaining structure during removal, hauls debris off-site
- Us: temp-tarps the roof opening, extracts standing water inside, dries interior, demos saturated materials, documents the loss
- Roofing contractor: permanent roof repair or replacement once tree is off and interior work is scoped
- Possible structural engineer: if tree penetrated or damaged structural members (rafters, trusses, load-bearing walls)
- Insurance adjuster: inspects after temp-work is in place; often does this quickly on tree-impact claims because they’re obvious cause-of-loss
What the insurance side typically looks like
- Tree impact is usually covered under homeowner policy as “sudden and accidental” damage — even if the tree was yours
- Tree removal from the structure is often covered up to a sublimit (typically $500-1,500 depending on policy); above that is out-of-pocket
- Tree removal from the yard (if not blocking entrance or on the structure) may not be covered at all
- Interior water damage from the opening is covered as part of the storm claim
- Business-income or ALE (additional living expenses) kicks in if you can’t live in the home during repair
What we tell homeowners up front
- Tree removal is not our scope — we work in parallel with a tree service, but we don’t cut or haul trees
- If the tree is still in the structure when we arrive, we scope what we can see and schedule the mitigation to start as soon as the tree is clear
- If the roof damage is extensive, we recommend a roofer named — and we work with that roofer on temp-dry-in and the permanent repair sequence
Common issues on tree-impact jobs
- Tree service and roofer scheduling — both busy during storm events; may add days to the overall timeline
- Water damage can be larger than it looks initially — water tracks along rafters and into cavities before the roof is open
- Attic insulation almost always needs replacement where the tree hit — it absorbs both water and tree debris
- Structural concerns may require engineer scope before permanent rebuild — adds time but necessary for safety
Utah storm-season preparation (what to do when)
Utah has distinct storm seasons: winter cold-event risk, spring runoff, summer thunderstorm cells, and fall transition. Here’s a seasonal preparation calendar for Salt Lake Valley homeowners:
| Season / timing | Prep activity | Why |
|---|---|---|
| Early fall (Sept-Oct) | Drain + insulate outside hose bibs | First freeze typically mid-Oct; frozen bibs rupture inside the wall |
| Early fall (Sept-Oct) | Clean gutters + verify downspout extensions reach 6+ ft from foundation | Fall leaves clog gutters; snow + rain accumulate; foundation water intrusion follows |
| Early fall (Sept-Oct) | Test sump pump + confirm backup power | Spring runoff is biggest sump demand; winter can freeze intake |
| Fall (Oct-Nov) | Attic + crawlspace inspection (insulation + ventilation + leaks) | Winter heating season starts; ice dams form from inadequate insulation |
| Fall (Oct-Nov) | Water heater age-check; flush sediment; check anode rod | Winter is peak water-heater usage; failures cluster during cold months |
| Fall (Nov) | Irrigation blown out + system shut off | Freezing water in system ruptures PVC + valves |
| Late fall (Nov-Dec) | Weatherstripping + attic hatch sealing | Reduces heated-air escape to attic (reduces ice-dam risk) |
| Late fall (Nov-Dec) | Winter emergency supplies ready (towels, buckets, flashlight, phone chargers) | Cold-event water emergencies happen when stores are closed |
| Mid-winter (Jan-Feb) | Attic condition check during a sustained cold snap | Catches ice-dam forming before major damage |
| Mid-winter (Jan-Feb) | Open cabinets under sinks during hard freezes (lets warm air reach pipes) | Pipes on exterior walls freeze; cabinet airflow helps |
| Early spring (Mar-Apr) | Pre-runoff inspection: foundation + grading + sump | Spring runoff is peak basement-intrusion season |
| Spring (Apr-May) | Roof inspection for winter damage (ice-dam fatigue, shingle lift from wind) | Catches issues before summer monsoon tests them |
| Early summer (May-Jun) | Pre-monsoon check: gutters clean + downspouts clear | Summer thunderstorm cells drop heavy rain fast |
| Summer (Jun-Aug) | Monitor A/C condensate line + drip pan | Peak A/C use; condensate failures happen |
| Summer (Jul-Aug) | Attic ventilation check (if swamp cooler used) | Swamp coolers add moisture to attic air; ventilation prevents condensation |
| Late summer (Aug-Sep) | Washing machine + dishwasher supply hose age check | Rubber hoses often fail during peak-use seasons |
Protection Plan + seasonal prep
- Our semi-annual inspection schedule includes fall-prep + spring-runoff-prep visits
- Specific items from the table above are covered during each inspection
- Written reminder of homeowner-DIY items between visits
Highest-ROI prep items
- Downspout extensions ($50 DIY) — prevents foundation water intrusion
- Smart leak sensors ($30-100 each) — catches leaks before they’re disasters
- Supply hose replacement to braided stainless ($20-40) — prevents the single most common sudden water event
- Water heater age-check — prevents end-of-life catastrophic failure
What to do during an active storm event
- Don’t go outside during active hail, high wind, or lightning
- Document damage with photos from safe locations (inside, protected areas)
- Shut utilities as needed (water main if active leak)
- Call for emergency response after safety is confirmed
- Don’t attempt to tarp a roof in active weather — wait
What to do after a storm event
- Document exterior damage with photos before touching anything
- Call insurance for FNOL
- Call us for mitigation if there’s interior water damage
- Call roofer for exterior damage
- Avoid predatory contractors who show up at the scene
If you want help planning seasonal prep for your specific home, our Protection Plan covers the twice-a-year inspection + reminders. Call (385) 247-9359.
Before the storm hits and after it passes — two different modes
Storm response splits cleanly into the hours before a forecast event and the hours after one. Each has its own checklist, and True Day runs both modes depending on when you call:
Before: Prevention mode
- Clean gutters and downspouts; verify discharge is away from foundation
- Check sump pump; test on manual cycle; verify battery backup if installed
- Walk the roof perimeter — missing shingles, exposed flashing, tree limbs over the house
- Window well covers in place; drains clear
- Verify basement window seals; check for prior leak staining
- Charge devices; locate flashlights; store essential documents up high
- If a severe weather watch is active and you want a pre-storm walkthrough, call — we schedule these when crews are available
After: Response mode
- Life safety first — no entry into structurally compromised areas, no energized water
- Call us immediately if there is active water intrusion, structural damage, or roof penetration
- Document conditions with photos before cleaning or moving anything
- Contact your insurance to open a claim; share the photo documentation
- If power is out but the structure is dry, mitigation can wait; if actively wet, we tarp and extract regardless of power status
- Temporary repairs (tarps, board-ups) get documented separately so they are reimbursable
The common mistake is treating storm response as reactive only. The 48 hours before a known weather event are when the preventable losses get prevented.